
Real Estate Agent · Bloomington, IN · Ellettsville, IN · Monroe County Ready to move — without the hassle?
Tired of agents who overprice, go quiet, and leave you coordinating everyone else? One plan. One point of contact. Straight answers.
Tired of agents who overprice, go quiet, and leave you coordinating everyone else? One plan. One point of contact. Straight answers.
Different goals, same promise: a clear plan and one person to call.
Meet the Team →New baby, same square footage. Sell and buy on one timeline — without moving twice.
Done paying rent near campus. Own your first home without overpaying.
The kids are gone. Net top dollar and move on with the least hassle.
Estates and acreage around Bloomington and Lake Monroe, marketed with discretion.
Two different journeys, each with its own timeline. We run the lender, inspector and title company — you get one team to call.
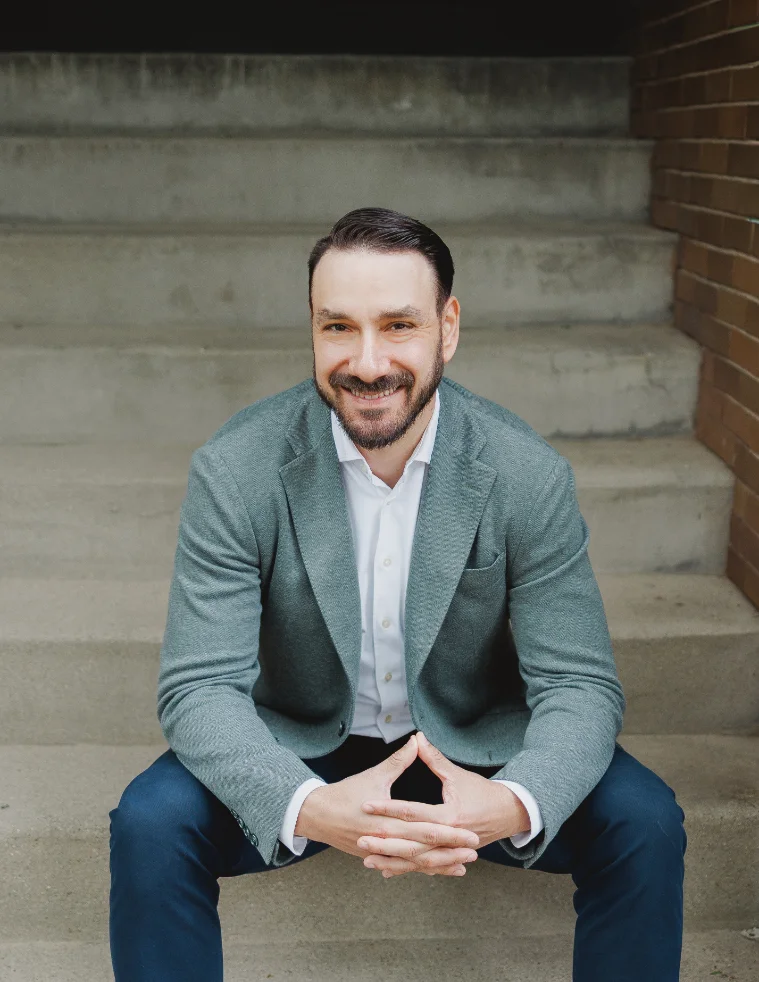
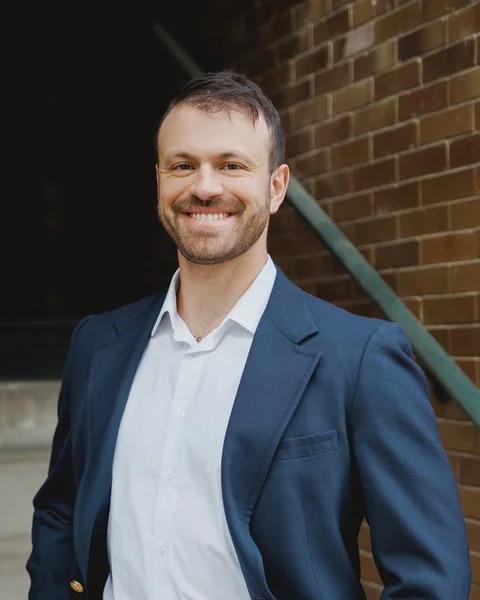
Same house, different outcome. Lance and Mason bring the pricing strategy, negotiation, local knowledge and steady guidance that turn a stressful move into a confident one. Backed by CENTURY 21 Scheetz and a dedicated Transaction Manager, you get a full team behind every step.
Price is the biggest lever in any sale or offer. We study recent comparable sales, current competition and how buyers are actually behaving in Bloomington and Monroe County, then set a price built to attract strong interest and hold its value through negotiation.
Clear communication, full transparency and real advocacy. You'll always know where things stand, what comes next and why we recommend it. We answer the hard questions straight and put your interests first.
By planning ahead. We map out every step from first conversation to closing so there are no surprises. With Kayla managing deadlines and documents, you get comfort and confidence that nothing falls through the cracks.
We're local experts who live and work here, and we're well respected among local industry leaders — lenders, inspectors, title companies and fellow agents. Those relationships help deals come together and stay together.
Negotiation is where outcomes are won or lost. We prepare with data, read the other side carefully and stay calm under pressure to protect your price, your terms and your timeline.
Calm, patient and honest. A move is a big life decision, so we act as counselors as much as agents — listening first, explaining your options and helping you decide with confidence.
Yes. We bring practical knowledge of construction, development and land use, including drainage and water flow, so you can spot issues early and see a property's optimal use before you buy, build or sell.
Former school counselor with a builder's eye for homes.
Meet Lance →IU alum. Honest pricing and same-day replies.
Meet Mason →Tracks every deadline, document and signature from contract to keys.
Meet Kayla →Real Monroe County costs, timelines and local surprises — in plain English.
Quick answers from local Bloomington, IN Realtors.
Meet the Team →It's smart if you plan to stay at least five years and the monthly payment fits your budget. Trying to time the market rarely works. In Bloomington, steady demand from IU keeps homes holding their value.
No. Under federal fair-lending law, a lender can't turn you down because of your age. Retirement income, Social Security and savings can all count toward qualifying. Many buyers in their 70s downsize to a single-level home near Bloomington or Ellettsville.
Real estate is land plus anything permanently attached to it, like a house, a garage or a fence. It's different from personal property, which you can move, like furniture.
It's an informal rule of thumb, and people use it a few different ways. The idea is always the same: keep a few months of payments in savings, have some money for a down payment, and don't stretch past what you can comfortably afford. Treat it as a quick gut-check, not a lending requirement.
Possibly, but it's tight. A $70,000 salary is about $5,800 a month before taxes. With 10–20% down and rates around 6–7%, a $300,000 home runs about $1,900–$2,100 a month including taxes and insurance. That's above the usual 28–30% guideline. Low debt or a bigger down payment helps.
Yes. On $100,000 a year, most buyers comfortably qualify for roughly $300,000–$400,000 at current rates, depending on debts and down payment. That covers a wide range of homes in Monroe County.
Get pre-approved by a lender. You'll know your real budget, and sellers will take your offer seriously. Next, pick a local agent to help you set a search plan.
Price. A home priced right from day one gets more showings and stronger offers. A home that's overpriced sits, then sells for less after price cuts.
It usually refers to the 30/30/3 rule. Spend no more than 30% of your gross income on housing. Have about 30% of the home's price saved in cash for the down payment plus a cushion. And keep the price at no more than about 3 times your yearly income. It's conservative, but it keeps you from becoming house-poor.
If you owned the home and lived in it for at least 2 of the last 5 years, you can generally exclude up to $250,000 of profit, or $500,000 if you're married filing jointly. Keep receipts for improvements, because they raise your cost basis. Ask a tax professional about your situation.
It can work, but it's a lot of work. You handle pricing, marketing, showings, negotiation and paperwork yourself. Industry data shows for-sale-by-owner homes typically sell for less than agent-assisted sales, which often erases the commission you saved.